Commercial Property Claims St. Petersburg
- Public Adjuster in St. Petersburg
- Hurricane & Windstorm Claims
- Roof Damage Claims
- Water & Plumbing Damage Claims
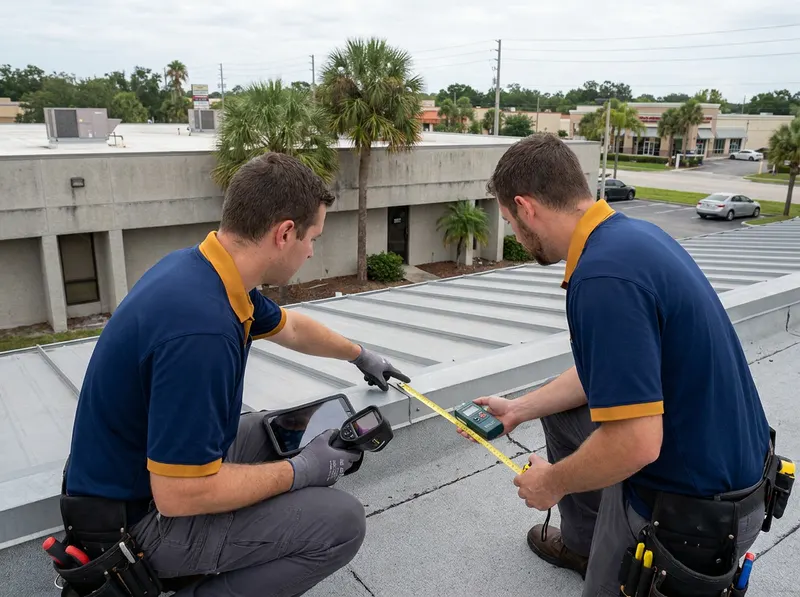
- Included: on-site inspection, damage measurement and photo/video documentation, policy review, sworn proof of loss preparation, and direct negotiation with the insurer's adjuster.
- How fast: initial inspection is typically scheduled within 1 to 3 business days; commercial claims commonly run 30 to 120 days depending on loss size and any business-interruption component.
- What it costs: Florida caps public adjuster fees at 20% of the recovered amount, dropping to 10% for claims from a declared emergency in the first year; the fee is a percentage of the settlement, not an upfront charge.
- What we take: a percentage of the additional settlement recovered, agreed in writing before work begins, with no fee paid on money you have already been offered in some fee arrangements.
- How to book: call Prestige Insurance Claims Adjuster at the number listed, or text a photo of the damage to start a free on-site review.
Commercial property claims differ from residential claims because they layer business-interruption loss, tenant considerations, and larger building components onto the standard structural damage assessment. A commercial policy separates the building limit, business personal property (equipment, inventory, fixtures), and lost income coverage, so a single roof breach at a Central Avenue retail unit or a Kenwood mixed-use building can generate three distinct claim categories that each require separate documentation. Prestige Insurance Claims Adjuster itemizes each category rather than filing one lump sum, because insurers apply different sublimits and deductibles to each.
St. Petersburg's commercial building stock spans century-old brick storefronts near Historic Roser Park, low-slope flat roofs common on Gulfport-adjacent Broadwater warehouses, and waterfront restaurant and marina structures around Snell Isle and Coquina Key that face wind-driven rain and storm surge exposure. Flat commercial roofs fail differently than pitched residential ones: ponding water, seam separation, and membrane punctures often produce interior damage before an owner sees it, and the National Weather Service Tampa Bay office (weather.gov/tbw) records the peak Gulf hurricane season as June 1 through November 30, when most St. Petersburg wind and water claims originate. Commercial deductibles in Florida frequently carry a separate percentage-based hurricane deductible, often 2% to 5% of the building's insured value, which on a $1 million warehouse can mean a $20,000 to $50,000 out-of-pocket figure that owners routinely overlook until the payout arrives short.
Decision guidance for business owners: if the insurer's offer covers the visible surface repair but ignores code-upgrade costs, hidden structural damage, or lost rental income, a public adjuster fits, the recovery gap usually exceeds the capped fee. If the loss is a small, single-item claim under the deductible, or the insurer has already paid the full documented amount, hiring representation adds little. A restaurant near the Pier District that loses two weeks of revenue after a water intrusion has a business-interruption claim that requires profit-and-loss records, payroll, and a period-of-restoration calculation; a vacant Allendale Terrace office with only cosmetic drywall staining does not. Florida's building code, enforced under the Florida Building Code and administered through Pinellas County permitting, can trigger 'law and ordinance' coverage that pays to bring an older Bahama Shores or Crescent Lake structure up to current standards during repair, a line item insurers commonly omit unless it is proven with code citations.
The process runs in plain steps. First, a licensed adjuster inspects the property and measures each damaged area. Second, the team reviews the full policy, including endorsements, sublimits, and the deductible structure. Third, the loss is documented with photos, moisture readings, and repair estimates aligned to standards published by organizations such as the Institute of Inspection Cleaning and Restoration Certification (iicrc.org) for water and mold work. Fourth, a sworn proof of loss and supporting file are submitted to the insurer. Fifth, the settlement is negotiated, and the Florida Department of Financial Services (myfloridacfo.com) provides the mediation and complaint channels available if the insurer disputes the amount. The U.S. Small Business Administration (sba.gov) also offers disaster loan programs that can run alongside an insurance claim after a declared event, and FEMA (fema.gov) guidance clarifies how those programs coordinate. Property owners can verify any adjuster's Florida license through the Department of Financial Services licensee search, and the National Association of Public Insurance Adjusters (napia.com) publishes conduct standards its members follow.
CallCommercial Property Claims pricing in St. Petersburg
| Public adjuster fee, standard commercial claim | Up to 20% of the recovered settlement (Florida statutory cap) |
| Fee for claims from a declared emergency, first 12 months | Up to 10% of the recovered settlement (Florida statutory cap) |
| Initial on-site inspection and claim review | $0 (free, no obligation) |
| Small commercial wind/water claim (typical settlement range) | $8,000 - $60,000, exact confirmed on-site |
| Larger commercial storm/fire claim with business-interruption (typical range) | $60,000 - $500,000+, exact confirmed on-site |
Exact price confirmed free on-site before any work.
Commercial Property Claims, questions, answered
How much does a commercial property claims public adjuster cost in St. Petersburg?
In St. Petersburg, Florida law caps the fee at 20% of the recovered amount for standard commercial claims and 10% for claims from a declared state of emergency during the first 12 months, under Florida Statute 626.854. Prestige Insurance Claims Adjuster agrees the exact percentage in writing before starting, and the initial on-site review is free.
Can Prestige Insurance Claims Adjuster handle business-interruption loss on a St. Petersburg commercial claim?
Yes. Business-interruption loss is a standard component of St. Petersburg commercial claims, covering lost income during the period of restoration. It requires profit-and-loss statements, payroll records, and a documented restoration timeline, all of which Prestige Insurance Claims Adjuster compiles as part of the claim file.
How long does a commercial property claim take in St. Petersburg?
A commercial property claim in St. Petersburg commonly takes 30 to 120 days, depending on loss size and whether business-interruption income is involved. Florida law requires an insurer to pay or deny a claim within 60 days of receiving proof of loss in most cases, and the initial inspection is usually scheduled within 1 to 3 business days.
Does my commercial policy's hurricane deductible affect my St. Petersburg claim payout?
Yes. Most St. Petersburg commercial policies carry a separate percentage-based hurricane deductible, often 2% to 5% of the insured building value, which is subtracted before payout. On a $1 million property that equals a $20,000 to $50,000 out-of-pocket amount, so Prestige Insurance Claims Adjuster confirms the deductible structure during the policy review.
How do I verify a public adjuster is licensed to handle my St. Petersburg commercial claim?
Any public adjuster working a St. Petersburg commercial claim must hold a Florida license, verifiable through the Florida Department of Financial Services licensee search at myfloridacfo.com. Prestige Insurance Claims Adjuster operates under Florida Statute 626.854, which requires the adjuster to represent the policyholder rather than the insurance company.