Hurricane & Windstorm Claims St. Petersburg
- Public Adjuster in St. Petersburg
- Roof Damage Claims
- Water & Plumbing Damage Claims
- Fire & Smoke Damage Claims
- What's included: full damage inspection, moisture and roof documentation, a line-item repair estimate, policy review, and negotiation with your insurer through payment.
- How fast: an on-site inspection is usually scheduled within 24-72 hours of your call; documentation packages are typically submitted within 7-14 days.
- What it costs: a contingency fee of roughly 10-20% of the recovered amount, with Florida law capping the fee at 10% for claims tied to a declared state-of-emergency event within the first year.
- What we take: nothing up front, the fee is a percentage of the settlement, so no recovery means no fee.
- How to book: call Prestige Insurance Claims Adjuster or text photos of the damage for a free claim review.
Hurricane and windstorm claims in St. Petersburg cover damage caused by named storms, straight-line winds, and the wind-driven rain that follows a breach, torn shingles, lifted roof decking, blown-off soffits, window and lanai screen failures, and interior water that enters once the envelope is opened. These claims are handled differently from a plain water or fire loss because Florida wind policies carry a separate hurricane deductible, usually 2% to 5% of the dwelling's insured value, which must be reached before the carrier pays. On a $400,000 home a 2% hurricane deductible is $8,000, so understanding which peril applies changes the entire math of a payout. The National Weather Service and NOAA storm records confirm the specific wind event and date, which anchors a claim to a covered peril rather than to gradual wear the insurer can deny under standard <a href="https://www.iii.org/article/understanding-your-insurance-policy">homeowners policy exclusions</a>.
Damage patterns vary by neighborhood, and the documentation reflects that. In Shore Acres and Coquina Key, low elevation near the water means wind-driven rain and surge overlap, so the file separates wind damage from flood damage, flood is covered only under a separate <a href="https://www.fema.gov/flood-insurance">National Flood Insurance Program</a> policy, and mixing the two is a common reason a claim is underpaid. In the 1920s bungalows of Kenwood and Historic Roser Park, older roof decking and original windows fail in ways a fast carrier inspection can miss. Waterfront homes on Snell Isle and Bahama Shores see screen enclosure, pool cage, and tile-roof uplift losses that require aluminum and tile pricing most desk adjusters underestimate. Old Northeast, Crescent Lake, Allendale Terrace, and Broadwater near Gulfport each present their own roof ages and tree-strike exposure, and every inspection is documented to the specific address rather than a template.
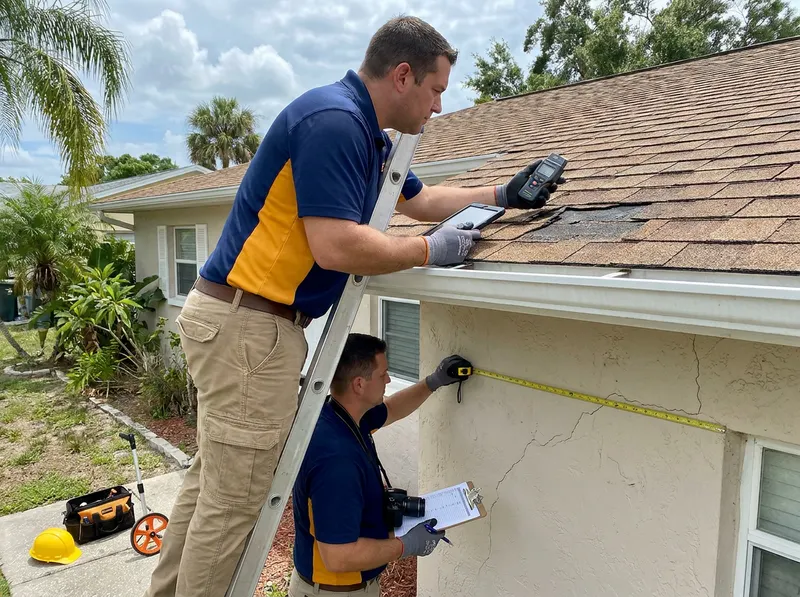
The process runs in a set sequence. First, an on-site inspection measures the roof, tests for moisture with meters, and photographs each elevation. Second, the policy is read line by line to confirm coverage, sublimits, and the hurricane deductible that applies. Third, a line-item estimate is built to current Pinellas County labor and material costs and submitted with the evidence package. Fourth, the insurer's response is negotiated, and if the carrier still underpays, the file supports appraisal or mediation. Florida's <a href="https://www.floir.com/">Office of Insurance Regulation</a> and the state's <a href="https://www.myfloridacfo.com/division/consumers">Department of Financial Services</a> set the licensing and consumer rules that govern this work, and every public adjuster must hold an active state license, which is verifiable online.
A public adjuster fits when the payout is far below the repair cost, when a claim is denied or stalling, or when the loss is large enough that a percentage fee is worth the recovery it produces, a full roof replacement, structural damage, or a whole-home water intrusion. For a small, obvious claim well under the hurricane deductible, hiring representation may not add enough to justify the fee, and that is stated plainly at the free review. The trade-off is straightforward: a share of the settlement in exchange for the documentation, valuation, and negotiation the policyholder would otherwise handle alone against a company with its own adjusters and engineers. Wind and storm claims in Florida also run on a filing clock, a notice of claim generally must be filed within one year of a hurricane under current statute, so a reopened or supplemental claim is time-sensitive.
CallHurricane & Windstorm Claims pricing in St. Petersburg
| Contingency fee, declared-emergency hurricane claim (first year) | capped at 10% of the amount recovered under Florida law |
| Contingency fee, non-emergency windstorm or reopened claim | roughly 10%-20% of the amount recovered |
| Initial claim review and on-site inspection | $0, free |
| Up-front / retainer cost | $0, fee comes only from a recovered settlement |
Exact price confirmed free on-site before any work.
Hurricane & Windstorm Claims, questions, answered
How much does a public adjuster charge for a hurricane claim in St. Petersburg?
A public adjuster in St. Petersburg typically charges 10-20% of the amount recovered, and for a claim tied to a declared state-of-emergency hurricane, Florida law caps that fee at 10% during the first year after the event. Prestige Insurance Claims Adjuster collects nothing up front, the fee comes only from money actually recovered.
What is the hurricane deductible on a St. Petersburg wind claim?
Most St. Petersburg homeowner policies carry a separate hurricane deductible of 2% to 5% of the dwelling's insured value, not a flat dollar amount. On a $400,000 home a 2% deductible is $8,000, and that amount must be reached before the insurer pays, so confirming which deductible applies is one of the first steps in every review.
Does a hurricane claim in St. Petersburg cover flooding?
A hurricane or windstorm policy in St. Petersburg covers wind and wind-driven rain, but not flood or storm surge, those are covered only under a separate National Flood Insurance Program policy. In low-lying areas like Shore Acres and Coquina Key the damage often overlaps, so a claim file separates wind damage from flood damage to avoid an underpayment.
How long do I have to file a hurricane claim in St. Petersburg?
Under current Florida statute, notice of a hurricane or windstorm claim in St. Petersburg generally must be filed within one year of the storm, with supplemental and reopened claims subject to their own deadlines. Because the clock is tied to the storm date documented by the National Weather Service, filing sooner protects the claim.
How do I confirm a St. Petersburg public adjuster is licensed?
Every public adjuster working a St. Petersburg claim must hold an active license issued by the Florida Department of Financial Services, and that license can be verified online through the state's licensee search. Prestige Insurance Claims Adjuster works only for the policyholder, never the insurance company.