Roof Damage Claims St. Petersburg
- Public Adjuster in St. Petersburg
- Hurricane & Windstorm Claims
- Water & Plumbing Damage Claims
- Fire & Smoke Damage Claims
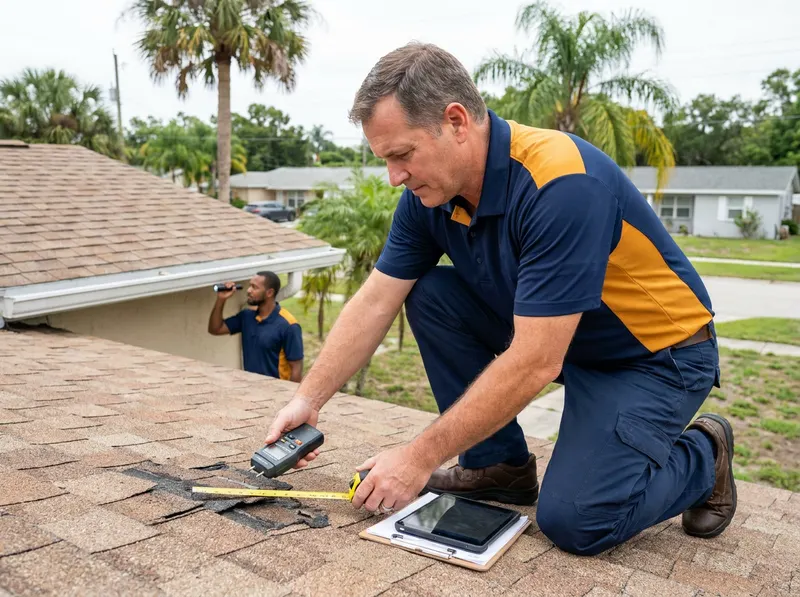
- Included: full roof inspection, moisture and slope measurement, photo and drone documentation, policy review, and negotiation of your roof damage claim with the insurer.
- How fast: an on-site roof inspection is typically scheduled within 2 to 4 business days; the claim timeline depends on the insurer, but Florida law requires most claims to be paid or denied within 90 days (Fla. Stat. 627.70131).
- What it costs: a contingency fee is a percentage of what is recovered, capped at 20% by Florida law, and 10% on claims from a declared emergency in the first year.
- What we take: nothing up front; the fee is a share of the settlement, so no recovery means no fee.
- How to book: call or text a photo of your roof damage for a free on-site St. Petersburg inspection.
Roof damage in St. Petersburg most often comes from hurricane-force wind, wind-driven rain, and hail during the June-to-November season tracked by the <a href="https://www.nhc.noaa.gov/">National Hurricane Center</a>. Older tile and asphalt-shingle roofs across Old Northeast, Historic Roser Park, and Kenwood take lifted shingles, cracked tiles, and displaced flashing; flat and low-slope roofs common on Coquina Key and Broadwater properties near the water pond and leak at seams. Prestige Insurance Claims Adjuster inspects the roof plane, attic, and ceilings, then binds each finding to a measurement, number of lifted courses, square footage of stained decking, moisture readings, because a documented loss survives insurer scrutiny far better than a general complaint.
The process runs in a short sequence. First, our team reviews your policy declarations to confirm whether roof coverage is replacement cost value or actual cash value, since an <a href="https://content.naic.org/consumer/home-insurance.htm">ACV settlement</a> depreciates the roof and pays substantially less than full replacement. Second, we perform an on-site inspection and document damage against wind-uplift standards referenced by <a href="https://www.floridabuilding.org/c/default.aspx">the Florida Building Code</a>. Third, we assemble an estimate line by line, tear-off, underlayment, flashing, and code-upgrade items owed under Ordinance or Law coverage. Fourth, we submit and negotiate. Wind and hail patterns are documented with reference to hail data from <a href="https://www.spc.noaa.gov/">the Storm Prediction Center</a> and roofing-material behavior described by manufacturers and by <a href="https://www.iibec.org/">the International Institute of Building Enclosure Consultants</a>.
A public adjuster fits a roof claim when the insurer's field adjuster called damage "cosmetic," applied heavy depreciation, or denied a leak as "wear and tear", situations frequent on the aging roofs of Allendale Terrace and Bahama Shores. Handling a straightforward, fully-paid roof claim without representation is reasonable; representation earns its fee when the gap between the offer and the true repair cost is wide. The trade-off is simple: the fee is a share of the recovery, so it matters only when a roof claim recovers more with documentation than without. Wind-mitigation credits and code items are among the most commonly missed, and are detailed by the <a href="https://www.floir.com/">Florida Office of Insurance Regulation</a>. Homeowners can verify any adjuster's license through the <a href="https://myfloridacfo.com/division/agents/">Florida Department of Financial Services</a>. Federal disaster declarations affecting St. Petersburg roof losses are posted by <a href="https://www.fema.gov/disaster/declarations">FEMA</a>, and roofing-material recycling and disposal after replacement is covered by <a href="https://www.epa.gov/smm/sustainable-management-construction-and-demolition-materials">the EPA</a>.
CallRoof Damage Claims pricing in St. Petersburg
| Contingency fee, standard roof claim | up to 20% of amount recovered (Florida statutory cap) |
| Contingency fee, declared-emergency claim, first year | up to 10% of amount recovered |
| On-site roof inspection & consultation | free |
| Supplement or reopened roof claim | same contingency structure on newly recovered amounts |
Exact price confirmed free on-site before any work.
Roof Damage Claims, questions, answered
How much does a public adjuster charge on a roof damage claim in St. Petersburg?
In St. Petersburg the fee is a percentage of what is recovered, capped by Florida law (Fla. Stat. 626.854) at 20% for most claims and 10% for claims tied to a declared emergency in the first year. Prestige Insurance Claims Adjuster charges nothing up front.
Can Prestige Insurance Claims Adjuster reopen a denied roof claim in St. Petersburg?
Yes, a denied or underpaid St. Petersburg roof claim can often be reopened as a supplement while it remains within Florida's statute of limitations, which is generally 1 year from the loss to file and up to 18 months to supplement under Fla. Stat. 627.70132.
Does a public adjuster handle both wind and leak roof damage in St. Petersburg?
Yes. Prestige Insurance Claims Adjuster documents both wind and hail damage and water intrusion on St. Petersburg roofs, distinguishing storm-created openings from excluded wear-and-tear so the leak is presented as a covered loss.
How long does a St. Petersburg roof damage claim take?
Florida law requires most property claims to be paid or denied within 90 days (Fla. Stat. 627.70131). A St. Petersburg roof inspection with Prestige Insurance Claims Adjuster is typically scheduled within 2 to 4 business days of your call.
Is a public adjuster the same as the insurance company's adjuster on a St. Petersburg roof claim?
No. The insurer's field adjuster works for the insurance company; a public adjuster works only for the policyholder. On a St. Petersburg roof claim, Prestige Insurance Claims Adjuster represents the homeowner and is licensed by the Florida Department of Financial Services.