Denied & Underpaid Claim Reopening St. Petersburg
- Public Adjuster in St. Petersburg
- Hurricane & Windstorm Claims
- Roof Damage Claims
- Water & Plumbing Damage Claims
- What's included: file review, re-inspection of the loss, new damage documentation, revised estimate, and a supplemental or reopening demand to your carrier.
- How fast: initial file review typically within 3-5 business days; a full reinspection package usually assembled in 2-4 weeks depending on damage scope.
- What it costs: a percentage of the NEW money recovered on the reopened claim, commonly 10%-20% in Florida; nothing recovered means nothing owed on that fee.
- What we take: your denial or payment letter, the original estimate, your policy declarations page, and photos of the damage.
- How to book: call Prestige Insurance Claims Adjuster or text photos of the damage and the denial letter for a free file review.
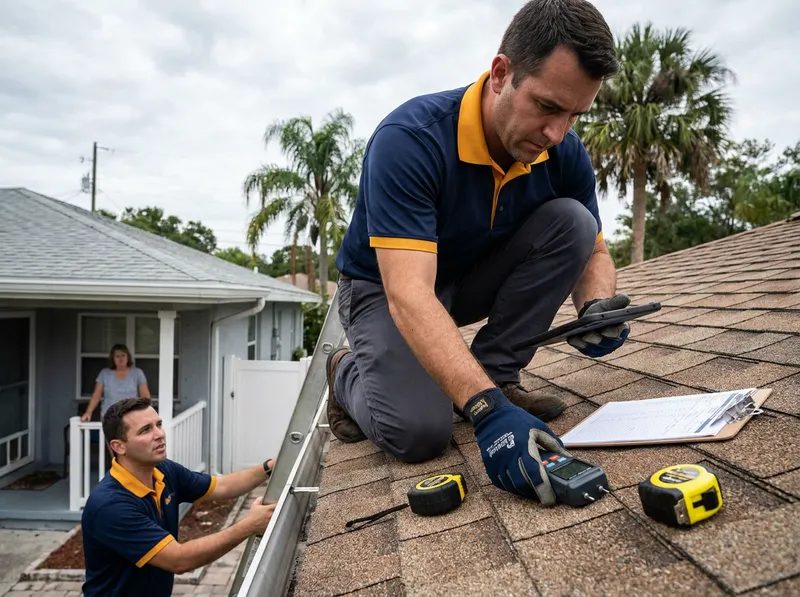
<p>A denied claim and an underpaid claim reopen through different doors, and the right door depends on what your carrier actually did. Florida statute 627.70132 sets a deadline to give notice of a supplemental or reopened property claim, and that window runs from the date of loss, so timing matters more than most St. Petersburg homeowners realize. A reopened claim revisits a claim the insurer closed or denied; a supplemental claim adds newly discovered or under-scoped damage to a claim they already paid something on. Both start with reading the file the carrier built the first time.</p><p>Underpayment is common after wind and water losses across Pinellas County because first-pass adjusters often miss what sits behind finished surfaces. In older homes around <a href="https://www.nps.gov/subjects/nationalregister/index.htm">Historic Roser Park</a> and Kenwood bungalows, an initial estimate might cover visible ceiling stains while missing saturated <a href="https://www.cdc.gov/mold/about/index.html">mold-prone framing</a> and plaster substrate. In waterfront zones like Snell Isle, Bahama Shores, and Broadwater, storm surge and wind-driven rain damage is frequently scoped as a single peril when the policy actually covers more. Reopening starts by re-inspecting the loss against the paid estimate line by line, then documenting the gap with photos, moisture readings, and a revised repair estimate priced to current St. Petersburg labor and material costs.</p><p>A reopening fits when the number is wrong or the denial rests on a factual mistake about the loss. It does not fit every situation: a claim denied for a clear policy exclusion, or one past the statutory notice deadline, may have no path forward, and an honest review says so before any work begins. The trade-off is straightforward. Handling it yourself keeps 100% of any increase but requires you to build the evidence and cite the policy language a carrier will accept. Using a licensed public adjuster costs a percentage of new money recovered but shifts the documentation and negotiation to someone who reads <a href="https://www.floir.com/">Florida property policies</a> daily. Under Florida law a public adjuster represents you, the policyholder, not the insurer, which the <a href="https://myfloridacfo.com/division/agents">Florida Department of Financial Services</a> licenses and regulates.</p><p>The reopening runs in a short sequence. First, our team pulls and reads your denial letter, original estimate, and policy declarations. Second, we re-inspect the property to find under-scoped or missed damage. Third, we document each item with photographs and moisture or damage measurements consistent with <a href="https://www.iicrc.org/">IICRC water-restoration standards</a>. Fourth, we build a revised estimate and a written demand. Fifth, we submit it to the carrier and negotiate the supplemental payment. Wind and hail losses are assessed against roofing methods documented by <a href="https://www.nrca.net/">roofing industry technical guidance</a>, and storm timing can be cross-checked against <a href="https://www.weather.gov/tbw/">National Weather Service Tampa Bay records</a>. Flood-versus-wind disputes, common in Shore Acres and Coquina Key, are separated because flood typically falls under a <a href="https://www.floodsmart.gov/">National Flood Insurance Program</a> policy while wind falls under your homeowner policy, and each requires its own reopening path. St. Petersburg building and permit records help confirm pre-loss condition and any repairs already made, and the <a href="https://www.consumer.ftc.gov/">consumer protection standards</a> that govern claim handling frame what a carrier owes.</p>
CallDenied & Underpaid Claim Reopening pricing in St. Petersburg
| File review and denial/payment letter analysis | no cost for the initial review |
| Underpaid claim supplemental (typical residential) | adjuster fee ~10%-20% of new money recovered |
| Denied claim reopening (documentation + demand) | % of recovery; no recovery, no fee on that amount |
| Small commercial property reopening | % of recovery, quoted after file review |
| Re-inspection and revised estimate package | included in the contingency fee |
Exact price confirmed free on-site before any work.
Denied & Underpaid Claim Reopening, questions, answered
Can a denied insurance claim be reopened in St. Petersburg?
Yes. A denied property claim in St. Petersburg can be reopened when the denial rests on a factual error, missed damage, or an incorrect scope of loss, provided it is still within Florida statute 627.70132's notice deadline. A claim denied for a clear, correct policy exclusion may have no path, and an honest file review says so first.
How much does it cost to reopen an underpaid claim in St. Petersburg?
In St. Petersburg the public adjuster fee for reopening an underpaid claim is a percentage of the new money recovered, commonly 10%-20% in Florida. The initial file review is free, and the fee applies only to additional dollars secured beyond what the carrier already paid.
How long do I have to reopen a claim after a storm in St. Petersburg?
Florida law sets the deadline for giving notice of a supplemental or reopened property claim, measured from the date of loss under statute 627.70132. St. Petersburg homeowners should have their file reviewed as soon as possible after a Pinellas County storm because a missed statutory window can end the claim regardless of merit.
What's the difference between a supplemental and a reopened claim in St. Petersburg?
In St. Petersburg a supplemental claim adds newly found or under-scoped damage to a claim your insurer already paid on, while a reopened claim revives one the carrier closed or denied. Waterfront losses in Snell Isle or Shore Acres often start supplemental when the first estimate missed damage behind finished surfaces.
Is Prestige Insurance Claims Adjuster licensed to handle claim reopening in St. Petersburg?
Yes. Public adjusters in St. Petersburg are licensed and regulated by the Florida Department of Financial Services, and a public adjuster represents you, the policyholder, not the insurance company. Prestige Insurance Claims Adjuster works for the property owner throughout the reopening process.