Fire & Smoke Damage Claims St. Petersburg
- Public Adjuster in St. Petersburg
- Hurricane & Windstorm Claims
- Roof Damage Claims
- Water & Plumbing Damage Claims
- What's included: full-property inspection, itemized structure and contents estimate, smoke and soot mapping, policy review, and negotiation with the insurer's adjuster.
- How fast: an on-site inspection is typically scheduled within 24-72 hours of your call, and emergency board-up or mitigation documentation begins the same visit.
- What it costs: a contingency fee, in Florida capped at 20% of the claim payment for non-declared-emergency claims and 10% for the first year of a declared state-of-emergency loss.
- What we take: nothing up front; the fee is a percentage of the settlement the insurer pays.
- How to book: call Prestige Insurance Claims Adjuster or text photos of the fire and smoke damage for a free on-site review.
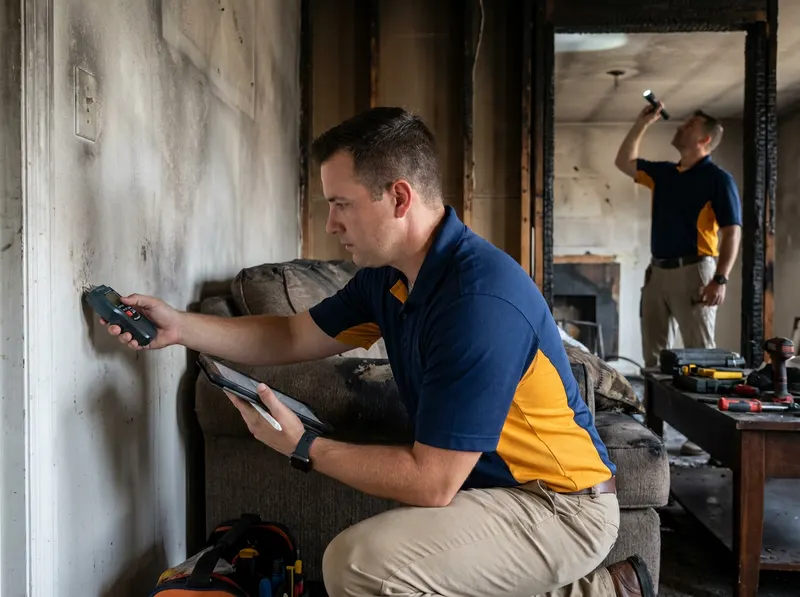
Fire losses in St. Petersburg rarely stop at the burned room. Smoke and soot travel through HVAC returns and wall cavities, so a kitchen fire in a 1920s Kenwood bungalow or a Historic Roser Park two-story can leave acidic residue on drywall, framing, and contents two floors up. That hidden migration is the part insurers most often underpay, and documenting it is the core work Prestige Insurance Claims Adjuster performs. Soot is measured room by room, HVAC contamination is noted, and salvageable versus total-loss contents are logged with make, model, and replacement cost so the estimate reflects the actual loss instead of a visual guess.
A fire claim splits into three parts most policies pay separately: dwelling (structure), contents (personal property), and additional living expenses for the time a home in Snell Isle or Bahama Shores is uninhabitable. The <a href="https://www.usfa.fema.gov/">U.S. Fire Administration</a> and the <a href="https://www.nfpa.org/">National Fire Protection Association</a> both note that smoke and water-mitigation damage frequently exceeds the flame damage itself, which is why an itemized, room-by-room record matters more than a single lump figure. Water used to extinguish the fire triggers its own drying and mold-prevention scope; the <a href="https://www.epa.gov/mold">EPA mold guidance</a> and <a href="https://www.cdc.gov/mold/">CDC mold information</a> both flag that Florida humidity accelerates mold growth within 24-48 hours, so wet framing in a Shore Acres or Coquina Key home must be documented and dried quickly.
A policyholder can file a fire claim alone, and for a small, single-room loss with an insurer that pays the full repair cost, that path works. A public adjuster fits better when the payout looks low against contractor pricing, when smoke has spread beyond the origin room, when contents are extensive, or when the claim has stalled. If the insurer's offer covers your licensed contractor's written estimate, you likely do not need representation; if it falls thousands short or ignores smoke and soot outside the burn room, an independent estimate and negotiation typically recovers more than the fee. Florida policyholder rights are set out in the <a href="https://www.floir.com/">Florida Office of Insurance Regulation</a>, and public adjuster licensing is verifiable through the <a href="https://www.myfloridacfo.com/division/agents/">Florida Department of Financial Services</a>.
The process runs in order: (1) an on-site inspection maps flame, smoke, soot, and water damage; (2) contents are inventoried and the structure is estimated with local Pinellas County labor and material pricing; (3) the policy is reviewed for dwelling limits, contents coverage, and additional-living-expense terms; (4) the complete package is submitted to the insurer; (5) negotiation continues until settlement. Restoration standards from the <a href="https://iicrc.org/">IICRC’s fire and smoke restoration guidance</a> and safe-cleanup steps from <a href="https://www.ready.gov/home-fires">Ready.gov’s home-fire recovery page</a> guide the scope so nothing citable is left off the estimate. Smoke odor and residue that reappear after a first cleaning are common in St. Petersburg’s older masonry homes near Crescent Lake and Allendale Terrace, and a re-inspection can reopen an underpaid claim.
CallFire & Smoke Damage Claims pricing in St. Petersburg
| Standard fire/smoke claim contingency fee | up to 20% of the claim payment (FL statutory cap) |
| Declared state-of-emergency claim, first year | up to 10% of the claim payment (FL statutory cap) |
| On-site fire & smoke inspection and estimate | no up-front charge; included in the contingency fee |
| Supplemental/reopened underpaid claim review | same contingency structure; no fee unless additional payment is recovered |
Exact price confirmed free on-site before any work.
Fire & Smoke Damage Claims, questions, answered
How much does a fire and smoke damage public adjuster cost in St. Petersburg?
In St. Petersburg the fee is a contingency percentage, capped by Florida law at 20% of the claim payment on a standard claim and 10% for the first year on a declared-emergency loss. Prestige Insurance Claims Adjuster charges nothing up front, and the fee comes only from money the insurer pays.
Does smoke damage outside the burned room get covered on a St. Petersburg fire claim?
Yes. Smoke and soot that travel through HVAC and wall cavities to other rooms are covered damage on most St. Petersburg homeowner policies, but they are frequently underpaid because they are not visible in a quick look. Prestige Insurance Claims Adjuster maps soot room by room so the estimate reflects the full spread.
Can I file my own fire claim in St. Petersburg instead of hiring an adjuster?
You can file a St. Petersburg fire claim yourself, and for a small single-room loss paid in full, that is fine. Representation makes the difference when the offer falls short of your contractor's estimate, when smoke spread beyond the origin room, or when the claim has stalled.
How do I confirm a St. Petersburg public adjuster is licensed?
Every public adjuster working a St. Petersburg fire claim must hold a Florida license, which anyone can verify through the Florida Department of Financial Services. Prestige Insurance Claims Adjuster operates under Florida licensing and welcomes that verification.
What about water damage from putting out the fire in my St. Petersburg home?
Water used to extinguish a St. Petersburg fire causes its own damage and is part of the same claim, including drying and mold prevention. Because Florida humidity can start mold within 24-48 hours, wet framing in areas like Shore Acres and Coquina Key is documented and dried promptly so it is not later disputed.